Three sessions in the moderator’s chair at Clean Buses UK last week, finishing with the closing keynote panel on authority and operator priorities. Plenty of audience questions, which made my job easier.
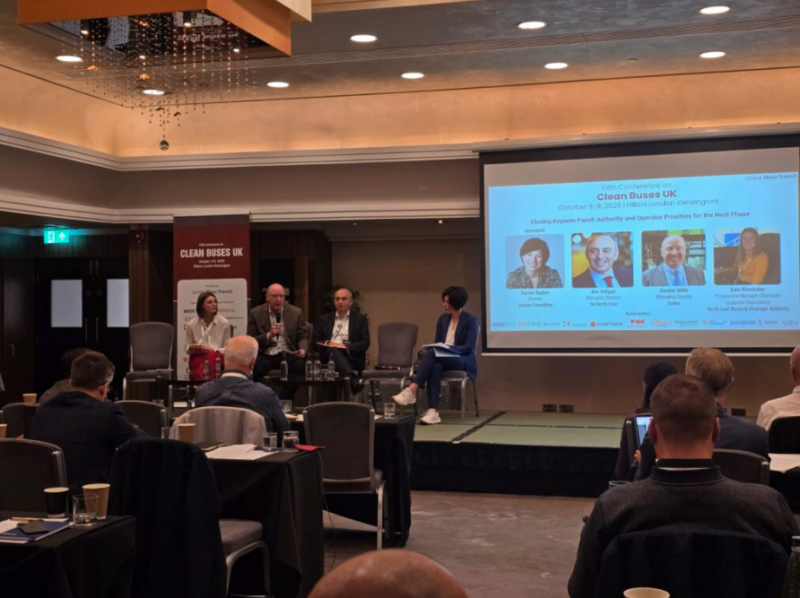
Rachel Hughes of Surbon Consulting moderates a panel discussion at Clean Buses UK in London, as speakers share their views on the UK’s transition to zero-emission buses with industry delegates
© Surbon Consulting
I particularly liked hearing the UK bus market described as fairly higgledy-piggledy: franchising, enhanced partnerships and devolution deals at different stages, and a national end date for new diesel buses still to be set. Things are moving, just not always in the same direction.
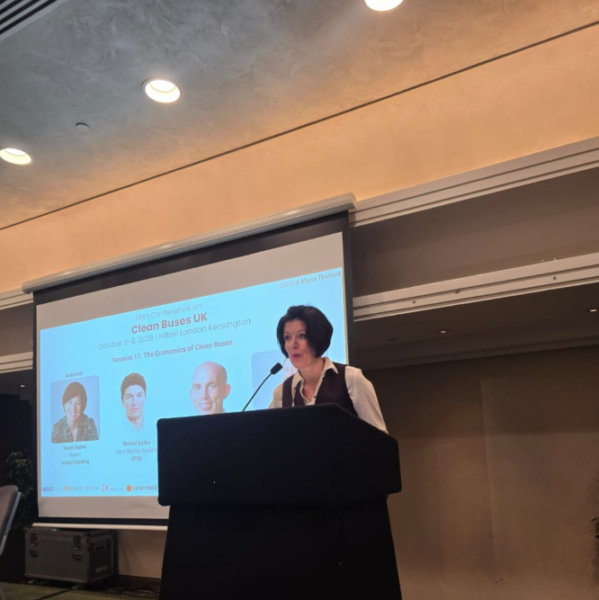
Rachel Hughes of Surbon Consulting at the lectern at Clean Buses UK in London, where she moderated three sessions, including the closing keynote panel on local authority and operator priorities
© Surbon Consulting
A few things that stood out, starting with Stephen Fidler’s DfT overview:
- Zero-emission buses made up more than half of new bus registrations in 2025, around 2,500 vehicles. They’re 23% of London’s fleet but 8% of the fleet in the rest of England.
- The dedicated ZEB grants (about £500m through ZEBRA since 2021) are giving way to broader local funding settlements. The order pipeline is being pulled together so manufacturers and operators can see beyond the next funding round.
- Mayors have committed to a minimum 10% social value weighting in all future bus procurement tenders, with standard social value questions to follow for the next big fleet tenders.
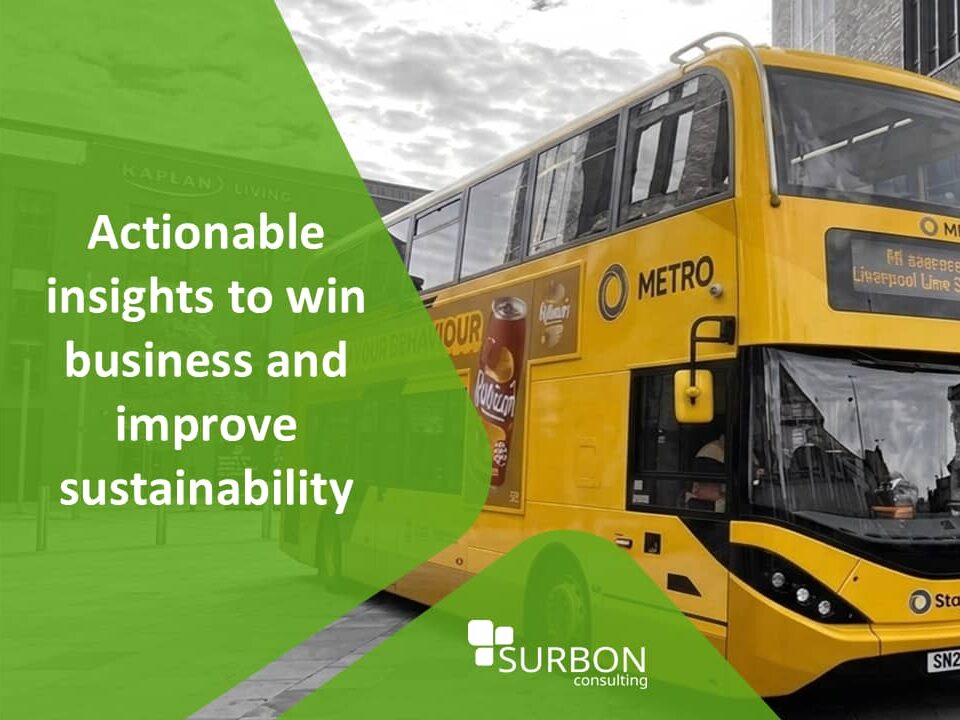
- Warrington’s Own Buses has picked up a franchised route in Liverpool City Region. Because its livery is already yellow, like the franchise colours, no rebrand is needed.
- TfWM and Translink are exploring a joint vehicle procurement in the coming months.
Thank you to Global Mass Transit for the invitation, and to the panellists for a lively discussion.
This article was originally published by Surbon Consulting.